
A 4-point home inspection is a focused look at a home’s four major systems, the roof, electrical, plumbing, and heating and cooling, that homeowners insurance companies use to judge risk before they issue or renew a policy. It does not cover the whole property the way a standard inspection does. This type of inspection is most common on older homes and in coastal states, and it usually takes under an hour. Below we explain what a 4-point inspection covers, why insurers ask for one, what tends to fail it, how to prepare, what it costs, and how it fits for homeowners outside the coastal markets.
What Is a 4-Point Home Inspection?
A 4-point home inspection is a targeted review of four major systems, the roof, electrical, plumbing, and heating, ventilation, and air conditioning (HVAC). Unlike a full home inspection that walks through the entire property, this one zeroes in on the systems most likely to cause an insurance claim. The inspector notes the age and condition of each system, looks for obvious safety concerns, and records the findings on a standardized form for the insurer.
The report is short and specific, which is exactly what an underwriter wants. A licensed and certified inspector performs the review, photographs each system, and documents the material type and remaining useful life. The goal is not to find every flaw in the home but to confirm the four systems are safe and sound.
What Does a 4-Point Inspection Cover?
A 4-point inspection covers the roof, the electrical system, the plumbing, and the HVAC, and little beyond them. Each system is checked for age, condition, and any obvious risk. Here is what the inspector looks at in each area.
Roof
The roof is often the first and most important part of the review, since a leaking or aging roof is the biggest red flag for insurers. The inspector records the roof’s material, age, and condition, and looks for missing or curling shingles, soft spots, sagging, and water stains. An asphalt shingle roof typically lasts 20 to 30 years, while tile or metal can hold up for 40 years or more, and many carriers will not write a policy on a shingle roof older than 20 years.
Electrical System
The electrical review looks at the panel, the wiring type, and the overall safety of the system. Home electrical systems cause roughly 51,000 fires a year in the United States, along with close to 500 deaths and about $1.3 billion in property damage, which is why insurers study wiring so closely. Outdated panels such as Federal Pacific or Zinsco, along with aluminum or knob-and-tube wiring, are common reasons a home is flagged or considered uninsurable.
Plumbing
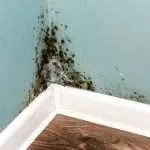
The plumbing check covers pipe materials, water pressure, and any signs of leaks or corrosion. Older materials like polybutylene (PB) pipes are prone to failure and can lead to denied coverage, so the inspector notes the pipe type throughout the home. Because slow leaks under sinks and around water heaters can also lead to hidden moisture, they sometimes point to the kind of problem that mold testing is designed to catch.
Heating and Cooling (HVAC)
The HVAC portion confirms the heating and cooling systems are present and working. The inspector checks the age, functionality, and drainage of the system, since a unit over 15 years old or one with poor drainage may need service or replacement. In some regions a home without working central heat can be disqualified from coverage entirely.
Why Do Insurance Companies Require a 4-Point Inspection?
Insurance companies require a 4-point inspection to gauge the risk of insuring a home before they issue or renew a policy. Homes that are 20 to 30 years old or older almost always trigger the requirement, because aging systems are more likely to fail and lead to expensive claims. A clean report can actually work in your favor, since it can speed up underwriting and unlock discounts by proving the systems are updated. Sellers sometimes order one too, and a pre-listing inspection can make an older home easier to insure and more attractive to buyers.
4-Point Inspection vs a Full Home Inspection
A 4-point inspection and a full home inspection both use a licensed inspector, but they serve different purposes and are not interchangeable. A standard home inspection examines the entire property for a buyer’s benefit, while a 4-point looks only at the four systems for an insurer. The table below shows the key differences.
| Feature | 4-Point Inspection | Full Home Inspection |
|---|---|---|
| Purpose | Insurance eligibility | Buyer due diligence |
| Scope | Roof, electrical, plumbing, HVAC | The entire home |
| Time to complete | 30 to 60 minutes | 2 to 4 hours |
| Typical cost | $75 to $200 | $300 to $500 or more |
| Required by | Insurers, mainly for older homes | Not required, but recommended |
| Report | Standardized insurer form | Detailed report with photos |
Sources: Redfin; Rocket Mortgage; HomeGuide.
What Will Make You Fail a 4-Point Inspection?
A 4-point inspection has no official pass or fail, but aging or unsafe systems are what make a home fall short in an insurer’s eyes. The inspector simply documents conditions, and the carrier decides whether to offer coverage, attach conditions, or decline. If a serious issue turns up, you can make repairs and schedule a re-inspection to document the fix. These are the findings that most often cause trouble:
- A roof near the end of its life, since many carriers will not insure a shingle roof over 20 years old
- Outdated electrical panels such as Federal Pacific or Zinsco, or aluminum and knob-and-tube wiring
- Polybutylene or corroded plumbing that raises the risk of water damage
- A heating or cooling system that no longer works or is well past its service life
- Past roof, electrical, or plumbing work completed without permits
How Do You Prepare for a 4-Point Inspection?
You prepare for a 4-point inspection by checking and documenting the same four systems the inspector will review, with no shortcuts or tricks involved. There is no way to game the result, so the goal is simply to fix what you can and prove the work you have already done. Follow these steps before the inspection:
- Inspect the roof, replace missing or cracked shingles, and clear the gutters.
- Open the electrical panel, make sure it is accessible, and confirm the breakers are labeled.
- Look under sinks and around the water heater for leaks or corrosion.
- Service the HVAC system, change the filters, and clear debris from the outdoor unit.
- Gather permits, receipts, and invoices for any past roof, wiring, or plumbing work.
- Clear access to the attic, the panel, the HVAC unit, and the space under sinks.
How Much Does a 4-Point Inspection Cost?
A 4-point inspection costs about $75 to $200 in most of the country, with many homeowners paying around $125, far less than a full home inspection. The price reflects the narrow scope and the short time on site, and it can rise for larger or more complex older homes. National figures like these are averages rather than our rates, and any inspection we quote is priced separately, so see our pricing page or contact us for a quote. Bundling a focused review with a full inspection often costs less than ordering each on its own.
How Long Is a 4-Point Inspection Good For?
A 4-point inspection is usually good for up to one year, though the accepted window varies by insurer. Many carriers want a report completed within the past 12 months, while some accept one up to three years old and others prefer a report no more than 30 to 90 days old. If you switch insurance companies, the new carrier may require a fresh report even if your current one is still within the accepted range. The safest step is to confirm the current timeline with your insurer or agent before you order one.
4-Point Inspections in Missouri and the Midwest
Where you live shapes whether a 4-point inspection ever comes up at all. The format is largely a coastal and Gulf-state tool, and it first took hold in Florida in the early 2000s as carriers tightened their rules on aging homes in hurricane-exposed areas. Across the Midwest and other inland regions, insurers more often rely on a full home inspection to size up a property’s condition.
For most local buyers, that makes a comprehensive inspection the practical choice. Our home inspection services examine all four of these systems and the rest of the home in a single visit. One detailed report tends to serve both the purchase and any insurance questions that follow.
Older homes are the exception to the inland pattern. An insurer writing a policy on a Missouri house built several decades ago may still request a 4-point report before agreeing to coverage. A thorough buyers inspection gives you and the carrier a complete view of that older home’s condition.
Rural properties add another wrinkle worth planning for. Homes outside municipal service often draw on private wells and on-site wastewater systems, so a full inspection can fold in add-on well water testing when a property needs it.
Septic-served homes deserve the same attention. A dedicated septic inspection checks the tank and drain field that a 4-point report never touches.
Frequently Asked Questions
Can a General Contractor Do a 4-Point Inspection?
Yes, a licensed general contractor can do a 4-point inspection in most states, along with a licensed home inspector, engineer, or architect. The person must hold an active license in the state where the inspection takes place and sign the report. Many carriers also want the inspector to hold a recognized certification, such as one from InterNACHI. Some insurers even accept reports from licensed electricians or plumbers for the systems they specialize in.
Can I Do a 4-Point Inspection Myself?
No, you cannot do a 4-point inspection yourself, because insurers only accept a report signed by a licensed professional. A carrier needs an independent, qualified opinion on the condition of the four systems, which a homeowner cannot provide for their own policy. You can certainly walk through the same systems ahead of time to spot obvious problems and avoid surprises. When it comes time for the official report, though, a licensed inspector has to complete it.
What Do 4-Point Inspectors Not Look For?
A 4-point inspection does not look for cosmetic flaws or problems outside the four core systems, and it skips specialized concerns entirely. It will not evaluate the foundation, appliances, windows, or drainage the way a full inspection does. Specialized issues such as radon, mold, sewer lines, and pests also fall outside its scope, so a homeowner who wants that coverage adds a service like radon testing on its own. In short, a 4-point is a quick snapshot for an insurer, not a complete picture of the home.
Can You Get Homeowners Insurance Without a 4-Point Inspection?
You can get homeowners insurance without a 4-point inspection on many newer homes, but older homes often cannot be covered until one is done. Whether a carrier asks for one depends on the home’s age, its location, the insurer’s own rules, and the condition of the property. Newer homes in lower-risk areas frequently skip the requirement, while homes past 20 to 30 years old usually do not. If your insurer requests one, completing it is typically the fastest path to a policy.
Covering All Four Points
A 4-point inspection is a focused, affordable look at the systems an insurer cares about most, the roof, electrical, plumbing, and HVAC. It is not a substitute for a full inspection, and for most buyers away from the coasts, a complete inspection is the more useful document, since it covers those four systems in depth and the entire home besides. Knowing what a 4-point report is, and when one is actually needed, helps you plan your coverage without paying for the wrong inspection.
We inspect all four of these systems and much more, delivering a clear, photo-documented report within 24 hours for homeowners and buyers across Mid-Missouri. If you are buying an older home or have questions about what your insurer needs, reach out to ARC Home Inspections and we will help you sort out the right inspection. You can call or text us any time to get started.