A home fails VA review when it does not meet Minimum Property Requirements, which test whether the property is safe, structurally sound, and sanitary. One clarification matters before anything else: the document that can fail a property is the VA appraisal, not a home inspection. A buyer’s home inspection produces no pass or fail result at all. Below we separate those two processes, explain the three pillars the appraisal measures against, give the specific failure threshold for each major system rather than just the category, cover how strict the standard really is, walk through the remedy paths including waivers and repair escrow, and show how to find these conditions before an appraiser documents them.
What Will Fail a VA Home Inspection?
What will fail a VA home inspection is any condition that leaves the property unsafe, structurally unsound, or unsanitary and that goes uncorrected before closing. The evaluation that applies the standard is the VA appraisal, and the standard is the set of Minimum Property Requirements the Department of Veterans Affairs publishes.
The recurring failures cluster in a short list. Inadequate heating leads it, since the property must maintain at least 50°F in every area containing plumbing. Unsafe electrical follows, covering exposed wiring, outdated fuse panels, and double-tapped breakers. Roof conditions come next, then water intrusion in basements and crawl spaces, then deteriorating paint on homes built before 1978, then wood-destroying insect damage or active infestation, then non-functional plumbing, then visible foundation movement, then broken windows, then access and drainage problems.
Most of those are correctable, and that is the part buyers miss while reading a list like this. A failure is a condition to be resolved rather than a verdict on the house. What separates a manageable finding from a dead transaction is whether the condition can be repaired at all, and a small number cannot.
Can You Fail a Home Inspection?
No, you cannot fail a home inspection. A general home inspection produces no pass or fail result, no grade, and no score. It produces a written record of observed conditions. Findings get reported as material defects, maintenance items, or safety concerns, and nobody issues a verdict.
That distinction is worth holding onto, because the phrase “failed the inspection” gets used constantly and describes something that does not exist. InterNACHI defines a material defect as an issue that may have a significant adverse impact on property value or that poses an unreasonable risk to people, and notes that a component near the end of its life cycle is not by itself a material defect. A report documents. A buyer decides.
VA appraisals work differently, and that is the source of the confusion. An appraisal carries a genuine compliance test, and a property either meets Minimum Property Requirements or it does not. When it does not, the loan stops until the condition is resolved. The table below sets the two processes side by side.
| VA Appraisal | Home Inspection | |
|---|---|---|
| Who requires it | The VA, on every purchase loan | Nobody at the VA; some lenders require one |
| Who is the client | The lender | The buyer |
| Purpose | Estimate value and confirm MPR compliance | Document the condition of visible, accessible components |
| Pass or fail result | Yes, in effect. MPR compliance is a threshold test | No. Findings are documented, never graded |
| Depth | Visible and accessible without specialized tools | 400+ components, with moisture meters and infrared imaging |
| Systems operated | None. Appraisers do not test HVAC or appliances | Heating, cooling, plumbing fixtures, outlets, appliances |
| Output | Appraisal report and a Notice of Value valid six months | Written condition report with photographs and severity notes |
| Effect on the loan | Can stop it until conditions are corrected | None directly; supports repair requests and negotiation |
Sources: U.S. Department of Veterans Affairs appraisal and Minimum Property Requirement guidance; VA Pamphlet 26-7, Lender’s Handbook; InterNACHI Standards of Practice and definitions.
A buyer’s inspection is therefore not a hurdle to clear. It is information you buy for yourself, and our buyer’s inspection exists to tell you what the appraisal never will. The standard that does carry a threshold deserves its own look.
What Are the VA Minimum Property Requirements?
The VA Minimum Property Requirements are the standards a property must meet to qualify for VA financing, and they organize around three pillars: safety, soundness, and sanitation. Every item an appraiser evaluates connects back to at least one of the three.
- Safety. Hazards that could directly harm occupants. Deteriorating lead-based paint on pre-1978 homes, exposed wiring, missing or loose handrails, unsafe stairs, non-functioning smoke alarms, and any condition creating immediate physical risk.
- Safety, continued: heating. The property must maintain at least 50°F in all areas containing plumbing. A wood stove serving as primary heat requires a secondary system meeting that threshold. There is no MPR for air conditioning, though an installed system must be operational.
- Soundness. Structural integrity across the foundation, roof, walls, and framing, with no visible evidence of major deterioration. The roof must offer reasonable future utility, durability, and economy of maintenance. Attics and crawl spaces must be accessible and properly vented.
- Sanitation. A continuous supply of potable water plus hot water for bathing, a safe method of sewage disposal, functional plumbing, and no condition exposing occupants to sewage, contamination, or significant mold growth.
- Site conditions. Safe year-round access by foot and vehicle from a public or private street with an all-weather surface, a recorded permanent easement where access is private, and drainage carrying waste and surface water away from the dwelling without ponding.
- Space and marketability. A residential dwelling of up to four units with adequate space for living, sleeping, cooking, dining, and hygiene, that would appeal to most buyers.
- Pest and rot. Any evidence of wood-destroying insects, fungus growth, or dry rot must be reported, and all damage must be repaired.
- Encumbrances. Compliance with local zoning, plus reporting of encroachments and of any dwelling located inside a high-voltage transmission or high-pressure pipeline easement.
Three of those standards changed on May 1, 2026, and most published guidance has not caught up. Detached non-habitable structures such as sheds and garages no longer have to meet MPRs, where previously a non-compliant shed had to be excluded from the appraised value. The certification requirement for permanently installed non-vented fireplaces and space heaters, including the oxygen-depletion sensor documentation, no longer applies to appraisals ordered after that date. Radon gas requirements were removed from the appraisal guidelines entirely. A detached structure that poses a health or safety hazard to occupants can still be flagged under the general hazard provisions, so the exemption is narrower than it first appears.
What Do VA Appraisers Flag?
VA appraisers flag conditions that are visible and accessible and that breach one of the three pillars. The useful question is not which systems get looked at, since the answer is all of them, but where the line sits inside each system. A roof three years from replacement passes. A roof with an active leak does not.
| System | Generally Passes | Generally Fails | Typical Remedy |
|---|---|---|---|
| Roof | Aging but intact, no leakage | Holes, missing covering, active leaks, no reasonable future utility | Repair, replacement, or a roofer’s certification |
| Heating | Any system holding 50°F where plumbing runs | No permanent heat source, or a wood stove alone as primary heat | Repair or install a compliant secondary system |
| Electrical | Older but safe and functional wiring | Exposed wiring, open junction boxes, unsafe panels, no power | Licensed electrician correction |
| Plumbing | Dated fixtures that operate correctly | Active leaks, non-functional fixtures, no hot water | Repair before closing |
| Foundation | Hairline or historic non-structural cracking | Visible movement, settlement, or compromised integrity | Engineering evaluation, then repair |
| Paint, pre-1978 homes | Intact painted surfaces | Chipping, peeling, or chalking paint | Remediation, with no cost-based waiver permitted |
| Pests and rot | No evidence of activity or damage | Active infestation, insect damage, fungus growth, dry rot | Treatment plus repair of all damage |
| Water and sewage | Adequate potable supply, safe disposal | Contaminated or insufficient supply, failing septic system | Testing, treatment, or system repair |
| Windows and openings | Older units that close and lock | Broken glass, openings that cannot be secured | Glazing repair or unit replacement |
| Access and drainage | All-weather access, water flowing away | No recorded easement, standing water at the foundation | Grading work or legal easement documentation |
Sources: U.S. Department of Veterans Affairs Minimum Property Requirements and appraisal guidance; VA Pamphlet 26-7, Chapter 12.
Reviewing the common problems that surface in an ordinary report shows how many of these conditions turn up on houses nobody would describe as distressed. Five systems generate the bulk of the questions.
Will a Bad Roof Fail a VA Appraisal?
A bad roof will fail a VA appraisal when it no longer prevents moisture from entering the home. The MPR standard asks whether the roof offers reasonable future utility, durability, and economy of maintenance, which is a lower bar than good condition and a higher bar than merely present.
Age alone does not fail. A twenty-year-old roof with intact covering and no evidence of leakage satisfies the standard, even though a buyer should budget for replacement soon. What fails is holes, missing shingles across an area, active leakage, or deterioration advanced enough that the appraiser questions remaining utility. An appraiser who raises that question can trigger a lender requirement for a professional roofer’s certification before the file moves. Knowing the visible warning signs of a failing roof lets a buyer anticipate that request rather than absorb the delay.
Will Peeling Paint Fail a VA Appraisal?
Yes, peeling paint will fail a VA appraisal on a home built before 1978. For those properties the presence of lead-based paint must be presumed, and any chipping, peeling, or chalking surface counts as defective paint requiring remediation before closing.
Two details make this the most predictable failure in the whole set. The trigger is the construction year, which a buyer can confirm before ever making an offer, and the VA permits no waiver based on the cost of remediation. On homes built in 1978 or later, deteriorating paint is generally treated as a maintenance observation rather than an MPR failure. Interior and exterior surfaces both count, including porch ceilings, window sashes, and outbuilding trim on structures still subject to review.
Will Mold Fail a VA Appraisal?
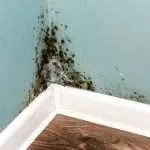
Significant mold growth will fail a VA appraisal under the sanitation pillar, and small isolated surface growth generally will not. The standard concerns whether occupants would be exposed to unsanitary conditions rather than whether any growth exists anywhere in the house.
Mold is also the clearest example of why an appraisal is a poor substitute for an inspection. Visible growth on a wall is what an appraiser can document. The far more common situation is moisture working inside a wall cavity or under a crawl space vapor barrier, producing conditions that will surface months after closing. Elevated moisture readings alongside a musty odor is the point where mold testing becomes the right next step, and neither the reading nor the odor appears in an appraisal report.
Will Termites Fail a VA Appraisal?
Yes, termites will fail a VA appraisal. Active infestation and wood-destroying insect damage must both be treated and repaired before the VA will issue a Notice of Value, which makes this a closing condition rather than an advisory note.
Location adds a second layer here. A wood-destroying insect report is required on the Notice of Value in areas where termites are prevalent, and Missouri sits in a moderate to heavy infestation probability zone, which makes that report a standing requirement statewide rather than a conditional one. The report covers wood-destroying organisms broadly, including carpenter ants, wood-boring beetles, and wood-decay fungi, and it examines sill plates, band joists, crawl space framing, and exterior wood in soil contact. Our termite inspection documents active activity and prior damage in the format lenders expect.
Will a Well or Septic System Fail a VA Appraisal?
A well or septic system will fail a VA appraisal when the water supply is not potable or sufficient, or when the sewage disposal system does not function safely. Both sit inside the sanitation pillar and both require documentation rather than observation.
Individual water sources qualify broadly, including dug wells, drilled wells, springs, cisterns, and holding tanks, provided the supply is adequate and safe, with filtration or chlorination added where needed. Shared wells carry an additional condition: a permanent recorded easement plus a maintenance agreement binding all signatory parties and their successors in title. Well water testing analyzes samples for coliform bacteria, nitrates, and other contaminants, and laboratory turnaround runs in days rather than hours, which makes it the item most likely to delay a rural closing.
How Strict Is a VA Home Inspection?
A VA appraisal is less strict than most buyers expect, because MPRs set a habitability floor rather than a quality benchmark. How hard it is to pass a VA inspection depends almost entirely on the property, and a reasonably maintained home clears the standard without drama.
The standard asks three questions: is it safe, is it sound, is it sanitary. It does not ask whether the kitchen is dated, whether the furnace has five years left, whether the layout is awkward, or whether the finishes are worn. Buyers arriving from stories about VA appraisals being punitive are usually hearing about a specific property type rather than the program.
Two categories draw nearly all the conditions. Older homes with accumulated deferred maintenance generate MPR flags because small individual failures add up to defective conditions, and pre-1978 construction brings the paint presumption with it. Vacant and foreclosed properties generate them because systems have been shut off, plumbing may have been compromised by freezing, and nobody has been present to notice a developing leak. Fixer-uppers sit at the far end of that spectrum, and a property needing significant work will generally not qualify for a standard VA purchase loan unless the work is completed first.
Do VA Appraisers Go in the Attic?
VA appraisers do not go in the attic in any meaningful way. Appraisers document conditions that are visible and accessible without specialized tools, and they are not required to enter crawl spaces either, or to check roof condition where the roof is not visible from the ground.
What the appraiser must do is note visible evidence from inside the dwelling, such as trapped moisture or staining on a ceiling, that would suggest a roof or structural problem. Attic insulation depth, ventilation balance, rafter condition, and evidence of past pest activity all fall outside that review. A fuller breakdown of what the appraisal does and does not cover sits with the VA loan requirements themselves.
How Often Are VA Home Loans Denied?
VA home loans get denied for two distinct reasons, and separating them matters more than any percentage. Property denials happen when the home does not meet MPRs. Borrower denials happen when the file does not clear underwriting on credit, debt-to-income, or residual income.
The practical difference is what each one can be fixed by. A borrower denial is frequently a lender overlay rather than a VA rule, since individual lenders set credit thresholds above the program minimum, and moving the file to another VA lender can resolve it. A property denial travels with the house. Switching lenders does not change whether a roof leaks or a pre-1978 home has peeling paint, and the same MPRs apply wherever the loan originates. Asking a lender directly whether a denial reflects a VA requirement or company policy is the fastest way to know which problem you have.
What Happens If a House Fails the VA Appraisal?
If a house fails the VA appraisal, the appraiser issues the report subject to repairs, and the loan pauses rather than ends. A subject-to condition is a specific item the report requires to be corrected before the VA will guarantee the loan, and the Notice of Value stays valid for six months, which gives real working room.
- Get the exact list of conditions. The appraisal report names each item specifically. Vague secondhand summaries cause more delay than the conditions themselves.
- Negotiate who completes and funds the work. Sellers frequently make MPR repairs, because the condition blocks the sale rather than merely inconveniencing the buyer. A repair framed as a loan requirement carries more weight than one framed as a preference.
- Address the cause, not the symptom. The VA expects the underlying mechanism corrected, particularly on moisture and pest findings where a cosmetic patch will not clear the condition.
- Request a reappraisal. Once the work is complete, the property can be reappraised without the conditions that held it back.
- Or pursue a waiver. After the Notice of Value is issued, the borrower may ask the VA to waive the repairs, with lender agreement, provided the property is safe, structurally sound, and sanitary enough to occupy. Documentation from a licensed professional supports that request.
- Or use a repair escrow. The lender holds funds for the work after closing, the property still has to meet MPRs, and the escrowed funds must be distributed before the VA guarantees the loan.
Lead-based paint remediation is the firm exception across all of these paths, since the VA permits no waiver based on what remediation costs.
Who Pays for VA Appraisal Repairs?
Who pays for VA appraisal repairs is a matter of negotiation rather than regulation. Nothing in the program assigns the cost, and the purchase contract plus whatever the parties agree to afterward decides it.
Sellers carry the work in most transactions, for a straightforward reason: the condition prevents this sale and will likely prevent the next one to any VA-eligible buyer. Buyers sometimes fund repairs on a property they badly want, and doing so before closing means paying to improve a house someone else still owns, which is worth thinking through clearly before agreeing to it. Splitting costs and applying a seller credit are both common middle paths. Reviewing how repair negotiations generally unfold helps a buyer decide which position to take.
What Failures Cannot Be Repaired?
The failures that cannot be repaired are the ones tied to location rather than condition. No amount of work changes where a property sits, which makes this category categorically different from everything else on the list.
Four situations fall here. A property in a FEMA-designated Special Flood Hazard Area requires flood insurance, and a property for which flood insurance is unavailable does not qualify. Properties within Coastal Barrier Resources System areas do not meet MPRs. A dwelling located inside a high-voltage electric transmission easement does not qualify, and neither does one inside a high-pressure petroleum or gas pipeline easement. Zoning conflicts and unresolvable access problems, such as a landlocked parcel with no recorded easement, belong in the same category. Identifying these before making an offer is the only remedy available, and every one of them is checkable in advance.
Can You Find MPR Problems Before the Appraisal?
Yes, you can find MPR problems before the appraisal, and ordering a home inspection first is the single most useful sequencing decision a VA buyer makes. A condition discovered before an appraiser documents it is negotiable. The same condition discovered after is a requirement.
The difference is leverage. A buyer holding an inspection report can ask the seller to address a peeling porch ceiling, a leaking supply line, or evidence of insect activity as an ordinary repair request, with room to negotiate a credit instead. Once that item appears on an appraisal as subject to repair, the negotiation is over and the work simply has to happen for anyone to close. Industry data shows 86% of home inspections reveal at least one issue that needs to be addressed, and buyers save an average of $14,000 through inspection-report negotiations, most of which is only available in the earlier window.
Scheduling an inspection before purchasing in the first days after the contract is signed leaves time to get contractor estimates, make a request, and still have the appraisal proceed on the lender’s schedule. Inspections also reach where appraisals do not, since we include thermal imaging and moisture meter testing at no extra cost and cover over 400 components rather than a visible-condition walkthrough.
One boundary is worth stating plainly. We do not perform VA appraisals and cannot make a property pass one. Only the VA-assigned appraiser decides MPR compliance. What an inspection does is surface the conditions that would trigger a finding, early enough for someone to do something about them.
How Long Does a VA Home Inspection Take?
A home inspection on a VA purchase takes 2 to 4 hours on site for a typical single-family property, and the VA appraisal runs 30 to 60 minutes. The two are separate appointments on separate schedules with separate reports.
Specialty services carry their own timelines rather than extending the appointment. A wood-destroying insect inspection runs 30 to 60 minutes depending on crawl space access. Well water analysis depends on laboratory turnaround measured in days. Septic evaluation varies with access to the tank lid and drain field. Our pre purchase inspection reports arrive within 24 hours with photographs, video, and written summaries, which matters when a 30 to 45 day contract period has to absorb an inspection, a negotiation, an appraisal, and any required repairs.
How Do I Pass a Home Inspection for Sale?
You do not pass or fail a home inspection when selling, and you can absolutely reduce what a buyer’s inspector and a VA appraiser find. Sellers listing into a market with VA-eligible buyers have a specific interest in clearing MPR-triggering conditions in advance, since those conditions will have to be corrected for any VA-financed sale to close.
Four items return the most for the least. Scrape and repaint deteriorating exterior and porch paint on pre-1978 homes. Correct visible electrical safety items such as open junction boxes, missing cover plates, and absent ground fault protection. Repair active plumbing leaks and confirm hot water. Address obvious roof damage and clear the gutters so water leaves the foundation. A pre-listing inspection identifies these while there is still time to schedule the work on your own terms rather than under a buyer’s deadline.
Missouri Conditions That Trigger MPR Findings
Missouri conditions that trigger MPR findings concentrate in four areas: wood-destroying insects, foundation movement, roof damage from freeze-thaw cycling, and rural water and wastewater systems. Local climate and geology drive all four, and they weight differently here than in drier or more temperate regions.
The insect requirement is the most consequential, because a wood-destroying insect report is a standing statewide condition on VA purchase loans rather than something triggered by what an appraiser happens to see. Humid summers and heavy soil contact on older housing stock both raise the likelihood of activity, and subterranean species work upward from the soil through sill plates and band joists where nothing is visible from inside the house.
Foundation movement runs second. Expansive clay soils swell and shrink with moisture cycling, and freeze-thaw action opens what the swelling started, which produces the stair-step cracking and door-frame racking that appraisers flag as visible structural evidence. The same freeze-thaw cycling works roof fasteners loose and opens sealant joints across a single winter, turning a sound roof into one with active leakage faster than a buyer relocating from a milder climate would anticipate.
Rural properties add the fourth. Private wells and septic systems are common outside the municipal service areas, and both fall under the sanitation pillar with documentation requirements attached. A septic inspection covering the tank, distribution box, and drain field is the standard way that condition gets satisfied, and it needs starting early because a failing drain field is slow and expensive to correct.
Frequently Asked Questions
What Is a 5 Point Home Inspection?
There is no standard five point home inspection. The recognized service is a four-point inspection, which evaluates the roof, electrical, plumbing, and heating and cooling systems, and it is used mainly by insurance carriers underwriting older homes rather than by lenders approving loans. A VA loan requires neither one. It requires a VA appraisal, and a full home inspection remains the buyer’s own optional due diligence.
Does a VA Appraisal Check for Radon?
No, a VA appraisal does not check for radon. The VA removed radon gas requirements from its appraisal guidelines effective May 1, 2026. Radon testing remains worthwhile independently, since the EPA and U.S. Surgeon General recommend testing all homes, with an action level of 4.0 picocuries per liter, and no appraisal of any kind will measure it.
Can a Seller Refuse to Make VA-Required Repairs?
Yes, a seller can refuse to make VA-required repairs. Nothing obligates a seller to complete work for a buyer’s financing. A refusal leaves the buyer to fund the repairs, pursue an MPR waiver where the property still qualifies as safe and sound, arrange a repair escrow with the lender, switch to a loan program with different property standards, or terminate under the contract.
Does a Fixer-Upper Qualify for a VA Loan?
A fixer-upper qualifies for a VA loan only if it already meets Minimum Property Requirements or the necessary work is completed before closing. A standard VA purchase loan does not finance repairs. A property needing significant work generally requires seller-completed repairs, a repair escrow arrangement, or a VA renovation product, and a condition report is essential for scoping any of those routes.
Can You Appeal a VA Appraisal?
Yes, you can challenge a VA appraisal through a Reconsideration of Value request submitted with supporting documentation such as comparable sales or a professional report. That process addresses valuation and factual errors. MPR conditions are resolved by correcting the condition, obtaining a waiver, or arranging escrow rather than by appeal. Your lender submits the request, so start there.
Does an IRRRL Refinance Require an Appraisal?
An IRRRL refinance does not typically require a new appraisal. The Interest Rate Reduction Refinance Loan is streamlined, which means the MPR review tied to a purchase appraisal generally does not apply. Cash-out refinances are treated differently, since they require a full appraisal and carry the same property standards a purchase does.
Where This Leaves You
A home fails VA review when it breaches safety, soundness, or sanitation, and the process that makes that call is the appraisal. Heating below 50°F where plumbing runs, unsafe electrical, a roof that no longer keeps water out, deteriorating paint on a pre-1978 home, active insect infestation, non-functional plumbing, visible structural movement, and contaminated or inadequate water are the conditions that come up again and again. Nearly all of them get corrected and the loan proceeds. The ones that cannot be corrected are tied to location rather than condition, and every one of them is checkable before you make an offer.
A home inspection has no pass or fail, which is the piece most buyers get backwards. It is not a test the house has to survive. It is information you buy for yourself, and on a VA purchase its greatest value is timing: a condition you find in week one is a negotiation, and the same condition on an appraisal in week four is an order. Three MPR standards changed on May 1, 2026, so confirm current guidance with your lender rather than relying on older articles, including the ones still describing radon as a VA appraisal item.
If you are under contract with a VA loan and want to know what an appraiser is likely to flag before one shows up, ARC Home Inspections is glad to talk through what to schedule and in what order.
Feel free to contact us with questions before you schedule, or call 314-948-3058.