
The buyer usually pays for a home inspection, since the inspection is meant to protect the buyer before they finalize one of the largest purchases of their life. The fee is paid out of pocket directly to the inspector, not rolled into the mortgage or closing costs. Still, the buyer is not always the one who pays, and the answer shifts with the loan type, the market, and what the two sides negotiate. This guide covers who pays for the inspection, when you pay, how the appraisal differs, the rules for VA loans, who pays for repairs, and what happens if the deal falls through.
Who Is Typically Responsible for Paying for a Home Inspection?
The buyer is typically responsible for paying for a home inspection, because the inspection is part of the buyer’s due diligence before finalizing the purchase. A standard home inspection runs from about $300 to $500, and can range from roughly $250 to $700 depending on the home’s size, age, and location, according to Redfin and Zillow. Because the report is primarily for the buyer’s benefit, confirming the condition of the property, the buyer normally covers that cost.
| Situation | Who Usually Pays | Notes |
|---|---|---|
| Buyer’s home inspection | Buyer | Paid out of pocket to the inspector, not through the mortgage |
| Seller’s pre-listing inspection | Seller | Ordered before listing to get ahead of issues |
| Home appraisal | Buyer | Required by the lender and paid with closing costs |
| VA termite (WDI) inspection | Buyer or seller | Since 2022 either can pay, and the seller often does |
| Repairs after the inspection | Negotiated | Seller, buyer, or shared, depending on the contract |
Sources: NAR; Redfin; Zillow; U.S. Department of Veterans Affairs.
Practices vary by state, and because Missouri follows a caveat emptor, or buyer-beware, approach, an independent inspection is a buyer’s main protection against inheriting hidden problems. Members of the American Society of Home Inspectors (ASHI) or the International Association of Certified Home Inspectors (InterNACHI) are the professionals trained to perform the work. Buyers usually arrange and pay for the inspection themselves, choosing from a full range of inspection services.
Do You Pay a Home Inspector Before or After the Inspection?
You typically pay a home inspector at the time of the inspection, either just before it begins or right after it is completed, rather than at closing. The fee goes directly to the inspector you hire, and it is not folded into your mortgage or closing costs. Some inspectors ask for payment upfront to lock in the appointment, while others collect it when the inspection is done and the report is delivered. You can review service and timing details on our pricing page.
Who Pays for the Home Inspection and Appraisal?
The buyer usually pays for both the home inspection and the appraisal, but they are two separate services with different purposes. A home inspection assesses the property’s condition and is the buyer’s choice, while an appraisal estimates the home’s market value and is required by the lender to approve the loan. The inspection is paid out of pocket to the inspector, and the appraisal fee is usually collected as part of closing costs.
Confusing the two is common, yet they protect different things. The appraisal protects the lender by confirming the home is worth the loan amount, while the inspection protects you by revealing defects a walkthrough would miss. An inspection from a certified inspector gives you a documented account of the home’s condition that an appraisal simply does not provide.
Who Pays for a VA Home Inspection?
For a VA home inspection, the buyer typically pays for any optional general inspection, while the required termite inspection can now be paid by either the buyer or the seller. The Department of Veterans Affairs (VA) does not require a general home inspection, though it does require an appraisal to confirm the home meets its Minimum Property Requirements. In many regions it also requires a wood-destroying insect (WDI) inspection, and a termite inspection is mandatory in more than 30 states for VA loans.
The payment rule changed recently. Before June 2022, VA buyers were prohibited from paying for the termite inspection, so the seller or another party covered it, but the VA now allows the buyer to pay where the inspection is required, and the seller still often does. Rural VA properties may also need a well water testing service and a septic check, since the appraisal verifies safe and functional water at the home.
Who Pays for a Home Inspection When Selling a House?
When selling a house, the seller pays for a home inspection only if they choose to order one, since the seller pays only for a pre-listing inspection they decide to get, and the buyer still pays for their own inspection. A pre-listing inspection lets a seller find and address problems before the home goes on the market, which reduces surprises and speeds up negotiations later. Scheduling a pre-listing inspection also gives buyers added confidence in the home’s condition.
There are also cases where a seller helps with the buyer’s costs. The seller may pay in the following situations:
- In a buyer’s market, where sellers offer concessions to attract offers
- When the seller orders a pre-listing inspection before going to market
- As a negotiated term written into the purchase agreement
- On a VA loan where a termite inspection is required and the seller agrees to cover it
Who Pays for Home Inspection Repairs?
No single party automatically pays for home inspection repairs, because repairs are negotiated between the buyer and the seller based on the findings and the terms of the contract. Sellers are rarely required to fix anything unless the contract calls for it, though some jurisdictions require repairs tied to safety, habitability, or financing, such as active water leaks or faulty wiring. In a buyer’s market a seller may agree to more, while in a competitive market buyers often limit requests to major items. Here is how the process usually unfolds after an inspection turns up problems:
- Review the inspection report to separate cosmetic items from serious defects.
- Decide whether to accept the home, negotiate, or walk away within your contingency window.
- Submit any repair request, credit request, or price reduction to the seller in writing.
- Wait for the seller to accept, counter, or decline, since they are rarely obligated to agree.
- Schedule a re-inspection if the seller agrees to make repairs, to confirm the work was done.
- Close on the home, or use your inspection contingency to exit the deal.
Buyers often prefer a credit at closing over seller-completed repairs, since it lets them control the quality of the work. When a seller does complete repairs, a follow-up re-inspection confirms the fixes held before you finalize the purchase.
Who Pays for the Home Inspection If the Deal Falls Through?
If the deal falls through, the buyer still pays for the home inspection, because the fee is paid to the inspector at the time of service and is not refunded. The inspector completed the work regardless of whether the sale closes, so the cost stays with the buyer who ordered it. The upside is that the report from your buyers inspection is yours to keep, and the information it contains can save you from a bad purchase. Walking away from a home with major problems is often far cheaper than the repairs you avoided, which makes the inspection fee money well spent even when a deal ends. If you had an inspection contingency, exercising it usually lets you recover your earnest money deposit.
Frequently Asked Questions
Is a Home Inspection Worth the Money?
Yes, a home inspection is worth the money, because it can reveal costly hidden problems and give you room to negotiate. Roughly 86% of inspections uncover at least one issue that needs attention, and buyers who negotiate afterward save an average of $14,000 through repairs, credits, and price adjustments. A modest inspection fee is small next to those savings, which is why a buyer’s home inspection is one of the smartest steps in the buying process. Skipping it means accepting the home as-is, along with any problems hiding inside the walls.
How Long Does a Home Inspection Take?
A home inspection takes at least two to three hours, and a smaller home of around 1,500 square feet often falls at the shorter end of that range. Larger homes, older properties, and homes with crawl spaces or multiple structures take longer. The timeline also depends on the home’s condition, since an inspector spends more time documenting a property with many issues. Buyers are encouraged to attend, which adds time but helps you understand the findings firsthand.
What Do Home Inspectors Not Look For?
Home inspectors do not look for problems hidden behind walls or inside systems they cannot access, and a standard inspection excludes specialized tests. A general inspection covers visible and accessible components, so it will not open walls, dig under a foundation, or evaluate anything sealed from view. Concerns like radon, mold, sewer lines, and pests fall outside a standard inspection, so buyers add a separate service such as radon testing when a property calls for it. Inspectors also do not judge cosmetic preferences or predict exactly when a system will fail.
Why Are So Many People Waiving Home Inspections?
So many people waive home inspections to make their offers more competitive, especially in fast-moving markets where sellers receive multiple bids. Waiving the inspection contingency can make an offer look stronger and simpler to a seller weighing several options. The trade-off is real risk, since a buyer who waives the inspection accepts the home without knowing what problems it hides. Even in a competitive market, an inspection contingency remains a valuable safety net that can prevent an expensive mistake.
Do Home Inspectors Get Paid Per Inspection?
Yes, home inspectors are usually paid per inspection, charging a flat fee for each job rather than a commission tied to the sale. This structure keeps the inspection independent, since the inspector has no financial stake in whether the deal closes. The fee typically reflects the size and complexity of the home, and specialized add-on tests are priced separately. Because payment is not linked to the outcome, you get an objective report either way.
What Is the Biggest Red Flag in a Home Inspection?
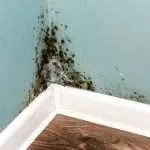
The biggest red flags in a home inspection are major structural, foundation, electrical, and water-related problems, since these are the most expensive and dangerous to fix. Foundation cracks, faulty wiring, roof damage, and signs of chronic moisture all point to costly repairs and are among the issues that most reduce a home’s value. Mold is another serious warning sign, and buyers who spot it often add mold testing to gauge the extent of the problem. Any of these findings is a reason to slow down, investigate, and negotiate before moving forward.
Knowing Who Pays
In most home purchases the buyer pays for the inspection, and that fee buys something valuable: an honest, documented look at the property before the sale is final. The picture changes with the situation, since sellers pay for pre-listing inspections, appraisals ride along with the loan, VA termite rules have their own logic, and repairs come down to negotiation. Knowing who pays for each piece helps you budget with confidence and avoid surprises at the closing table.
We provide thorough buyer’s and pre-listing home inspections for homeowners, buyers, and sellers across Mid-Missouri, with a clear, photo-documented report delivered within 24 hours. If you are preparing an offer or getting a home ready to list, reach out to ARC Home Inspections and we will walk you through scheduling and what to expect. You can also call or text us with any questions before you book.